
If the deuterium-tritium fusion core were free (magnets, blankets, heating systems, handed to you at zero cost) the plant would still produce electricity at around $29/MWh. That is nearly three times the 1-cent per kWh target we are interrogating. The cost uncertainty is not in the turbines or the buildings. It is in the fusion core. And the range of estimates for that core is large. This dispatch will examine the theoretical cost-of-electricity floor in a power plant where the fusion core, the largest unknown, is ignored.
Published estimates for a commercial fusion plant range from $47/MWh for an optimistic nth-of-a-kind advanced tokamak (ARIES-AT, Najmabadi et al., 2006) to $160+/MWh for a first-generation EU-DEMO (Entler et al., 2018), with most serious estimates landing between $50 and $130/MWh (Sheffield & Milora, 2016). Recent analysis from Cambridge suggests early fusion plants will exceed $150/MWh even with production learning (Lindley et al., 2023).
Cost estimates for commercial fusion projects are largely kept under wraps. Experts disagree on the eventual costs. A recent Nature Energy analysis compiled first-of-a-kind CAPEX estimates from a range of experts and the literature and found a range of $1,400 to $43,000 per kilowatt, a 30x spread (Tang et al., 2026).
We are seeking corridors for fusion to have a revolutionary price point: 1 cent per kilowatt-hour. If we start by accounting for the components we’re certain about and that exist today at commercial scale, we establish the lower bound on what fusion electricity can cost.
The question we ask: what does the plant cost if the fusion core were free?
Thermal Conversion: The Heat Engine
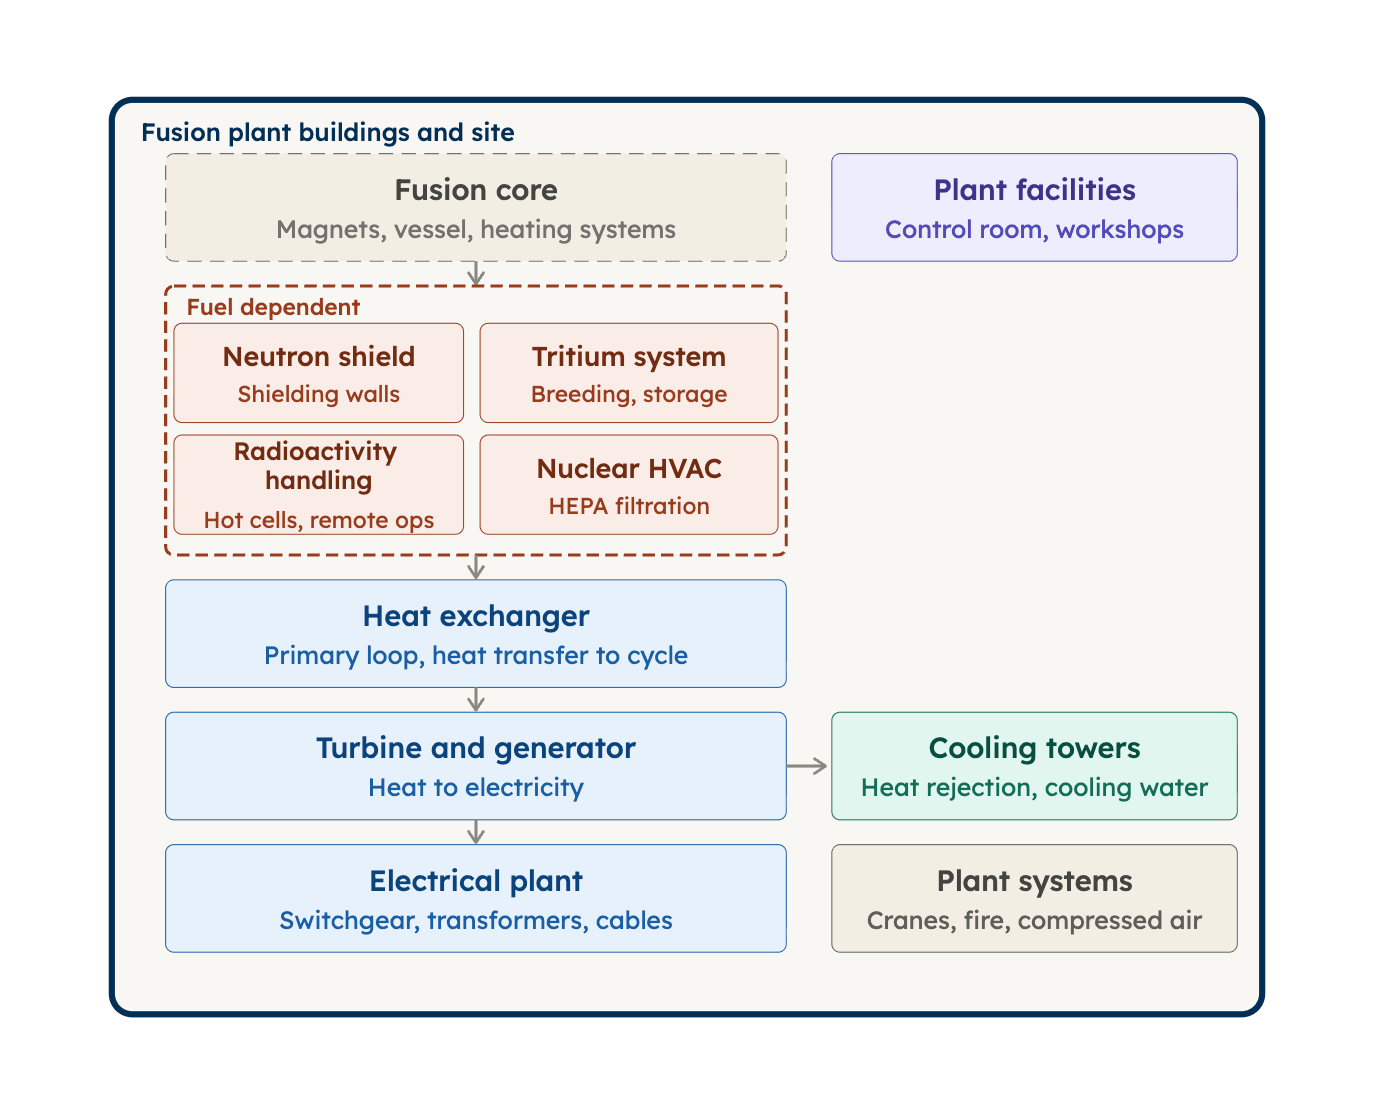
A fusion plant must convert the energy generated in the fusion core to useful electricity. For this purpose, most projects envision using a heat engine (turbines, generators, cooling towers) in addition to a switchgear, a control room, and a building to put it all in. These components are mature industrial hardware, with no real price uncertainty or learning rates. Beyond the equipment itself, a plant incurs indirect costs (engineering, project management), owner’s costs (staff recruitment and training), supplementary costs (shipping, spares, insurance, decommissioning provisions), financing charges, and ongoing operations and maintenance. All of these are well-characterized from existing power plant experience.
Using the 1costingfe techno-economic model, we can approximate costs for these components in a 1 GWe plant. The table below uses a supercritical CO2 Brayton cycle, which gives the lowest floor of the three options we modeled (Rankine, sCO2, and combined cycle). All numbers in this post can be reproduced with the companion script.
The table below is for a D-T plant. The thermal cycle is the only conversion pathway considered here (direct energy conversion is analyzed separately in the follow-on dispatch). When the same configuration is run for aneutronic fuels, the BOP equipment subtotal is essentially unchanged (roughly $386M), because turbine, heat-rejection, and electrical hardware all scale with thermal-electric power rather than fuel choice. The fuel-related cost differences show up in buildings and staffing (covered later), not in BOP equipment:
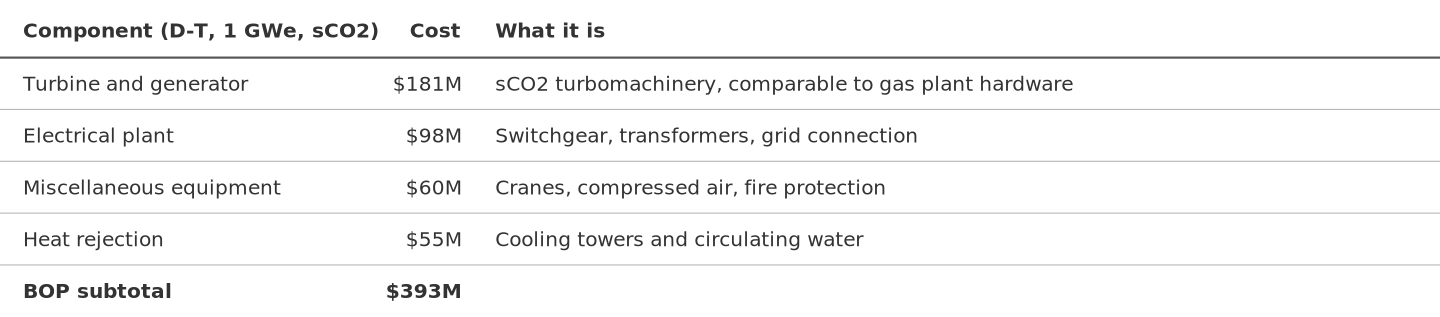
The BOP equipment is priced from NETL’s Cost and Performance Baseline for Fossil Energy Plants (DOE/NETL-2022/3575) and the ARIES cost account documentation (Waganer, UCSD-CER-13-01, 2013), adjusted to 2024 dollars.
The Rest of the Plant
Buildings are not fuel-independent. A fusion plant includes roughly 18 distinct buildings and site structures: reactor building, turbine hall, heat exchanger building, cryogenics facility, power supply building, control room, maintenance shops, and others. About half of these (turbine hall, cryogenics, switchgear building, assembly hall) are the same regardless of fuel. The other half (reactor building, hot cell, ventilation systems, fuel storage, site improvements) vary with the radiation and tritium hazards of the fuel. A D-T plant needs biological shielding walls in the reactor building, a hot cell for remote handling of activated components ($90M by itself), tritium containment barriers, and nuclear-rated HVAC with HEPA filtration. An aneutronic p-B11 plant needs none of these: the reactor building is a standard heavy industrial crane hall, there is no hot cell, and the HVAC is conventional. The result is a range from $359M (p-B11, industrial-grade) to $574M (D-T, enhanced-industrial). We return to the fuel-specific breakdown below.
On top of the direct costs, there are indirect costs (engineering, project management, roughly 20% of direct costs), owner’s costs, supplementary costs (shipping, spares, insurance, decommissioning provisions), and financing charges. For a 1 GWe D-T plant with a free fusion core, these add up: $574M buildings + $393M BOP equipment + $195M indirects + $39M owner’s costs + $220M supplementary costs, plus $280M interest during construction, for a total capital cost of $1,700M. A plant also needs staff, roughly 30 to 80 full-time employees at 1 GWe scale depending on fuel choice and the associated radiation protection requirements, costing $18-40M/year in loaded operations and maintenance (O&M). The LCOE is the annualized capital charge plus O&M, spread over the plant’s lifetime energy production. All of these costs are included in the LCOE floors reported below.
Quantifying the Deuterium-Tritium Cost Floor
Deuterium-tritium (D-T) is the mainstream fuel choice for fusion. It produces 80% of its energy as 14.1 MeV neutrons, which activate structural components and require heavy shielding, and it uses radioactive tritium, an environmental hazard if it leaks into groundwater. Even with a free fusion core, a D-T plant still needs buildings with radiation shielding, tritium containment with secondary barriers, hot cells for remote handling of activated components, and nuclear-rated HVAC. These requirements are driven by the hazards themselves (neutron activation and tritium inventory), not by regulatory classification. The buildings cost $574M at 1 GWe, and the plant requires roughly 80 staff for radiation protection, tritium handling, and the maintenance procedures these hazards demand.
For a 1 GWe D-T tokamak at standard financial assumptions (7% weighted average cost of capital (WACC), 85% availability, 30-year life, 6-year construction), the Levelized Cost of Electricity (LCOE) floor with a free fusion core is $29/MWh, nearly three times the 1-cent target ($10/MWh). The overnight capital cost of this core-free plant is $1,723/kW.
For context, the fully costed D-T tokamak at the same conditions comes in at $83/MWh. The fusion core accounts for about two-thirds of that. But the remaining third ($29/MWh of buildings, BOP, staffing, and financing) already exceeds the 1-cent target by itself. No improvement in the fusion core can close a gap that lives outside the core.
Lowering the D-T Floor
The $29/MWh floor assumes a single 1 GWe plant built with commercial project finance. Can we push it down to $10/MWh by improving the parameters that are independent of the fusion core? The parameters are:
Scale spreads fixed costs (buildings, staff, indirects) over more megawatt-hours
Availability produces more energy per dollar of installed capital
Financing cost (WACC) determines the annual capital charge rate
Construction time determines interest during construction
Plant lifetime determines how many years of revenue amortize the capital
Staffing determines O&M cost, which can be half the floor at large scale
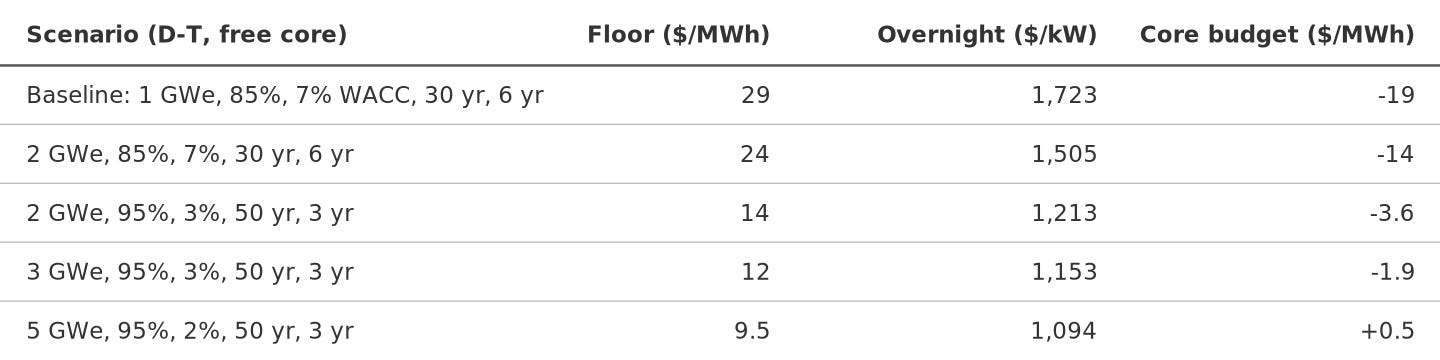
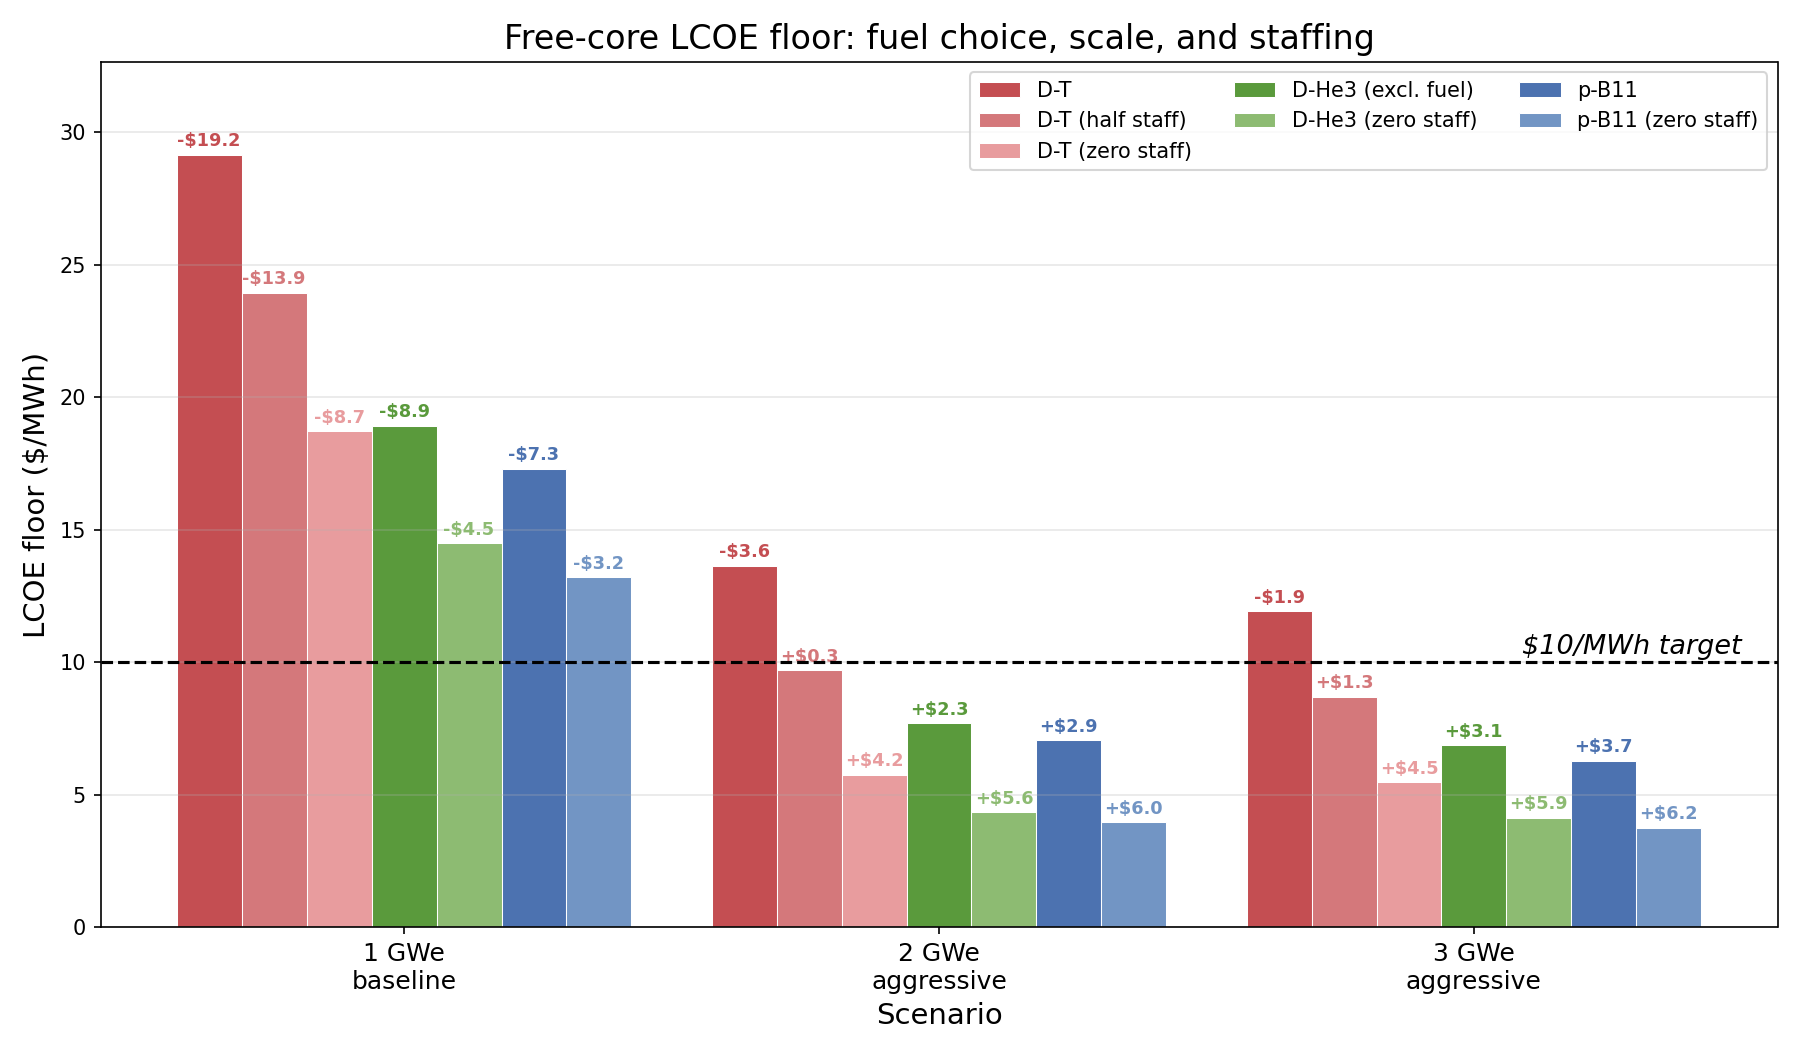
Even at the most aggressive conditions (a 5 GWe plant with 95% availability, 2% WACC, 50-year life, and 3-year construction), the D-T floor barely crosses $10/MWh, leaving only $0.5/MWh of budget for the fusion core. That translates to roughly $40/kW of overnight capital for the entire core: magnets, heating, vacuum vessel, structure, power supplies, and installation. For reference, a single large superconducting magnet costs more than this. The D-T floor cannot be pushed low enough to make room for the core.
The reason is the buildings and staffing. D-T buildings cost $574M at 1 GWe because neutrons and tritium demand shielding, hot cells, containment barriers, and nuclear-rated HVAC. D-T staffing runs to 78 FTE because those hazards require health physics technicians, tritium processing personnel, radwaste handlers, and hot cell operators. These costs scale down with plant size but never disappear. They are structural consequences of the fuel choice, not of the plant design.
Reducing D-T Staffing
At the most aggressive conditions in the table above (5 GWe, 2% WACC), the D-T floor is $9.5/MWh. O&M staffing accounts for roughly half of that. D-T staffing is high (78 FTE at 1 GWe) because of the radiation and tritium hazards: health physics technicians (10-15), tritium processing and accountability personnel (10-20), radioactive waste handling (5-10), and hot cell operators for remote maintenance of activated components. Can automation close the remaining gap?
Highly automated operation (already deployed in semiconductor fabs, chemical plants, and automated factories) could reduce a conventional thermal plant from 30 to 15 full-time employees. But a D-T plant is not a conventional thermal plant. The radiation-specific roles resist automation differently: hot cell remote handling is already robotic, but the programming, supervision, and exception handling still require humans. Tritium accountability is a regulatory function. Health physics coverage is required whenever personnel enter controlled areas, and someone has to enter for the maintenance that remote handling cannot reach.
What prevents going to zero, true lights out operation? The remaining functions are grid dispatch (mostly SCADA-automated already), routine maintenance, unplanned fault response, regulatory compliance, and security. Routine operations are automatable with current technology. The binding constraint is the unplanned event: a novel failure mode that requires judgment under uncertainty. If current automation technology trajectories hold (humanoid robotics for physical intervention, AI agents matching human expert judgment in relevant domains), the binding constraint shifts from technical capability to regulatory accountability. Utility-scale grid infrastructure may still require human accountability for some period regardless of what the technology can do. That is likely the imposed floor on staffing, not technological feasibility.
How much does staffing need to fall to cross the $10/MWh threshold? At the aggressive 5 GWe conditions, the D-T floor is $9.5/MWh, of which $5.2/MWh is O&M. The capital-only floor is $4.3/MWh, well below the target. D-T reaches $10/MWh at this scale with current staffing levels. At 2 GWe (a more realistic near-term scale), the capital floor is $5.8/MWh, and staffing needs to fall to about 54% of current levels (roughly 42 FTE instead of 78) to reach $10/MWh.
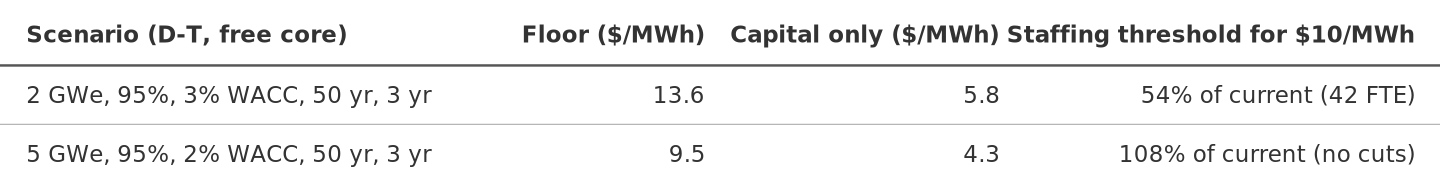
Halving D-T staffing from 78 to 39 FTE is not lights-out operation. It is a moderate automation scenario: SCADA-automated grid dispatch, reduced shift coverage, streamlined radiation protection procedures. The radiation-specific roles resist full elimination (as long as humans enter the plant, health physics coverage is required; as long as tritium is on site, accountability is required), but a 50% reduction is within reach of current industrial automation technology. The capital cost of the automation itself (SCADA upgrades, remote monitoring, robotic inspection) is on the order of $15-30M, adding less than $0.2/MWh at these conditions, small relative to the $4/MWh saved.
This means the D-T floor can reach 10/MWh under aggressive automation conditions, but only with large scale (2+ GWe), favorable financing, and moderate staffing automation. The margin is thin and leaves negligible budget for the core.
Fuel Choice Is Fundamental to the Floor
The D-T floor resists every parameter we have pushed: scale, financing, construction time, and staffing automation. The constraint is not the plant parameters. It is the fuel.
Different fuel choices result in different floors.
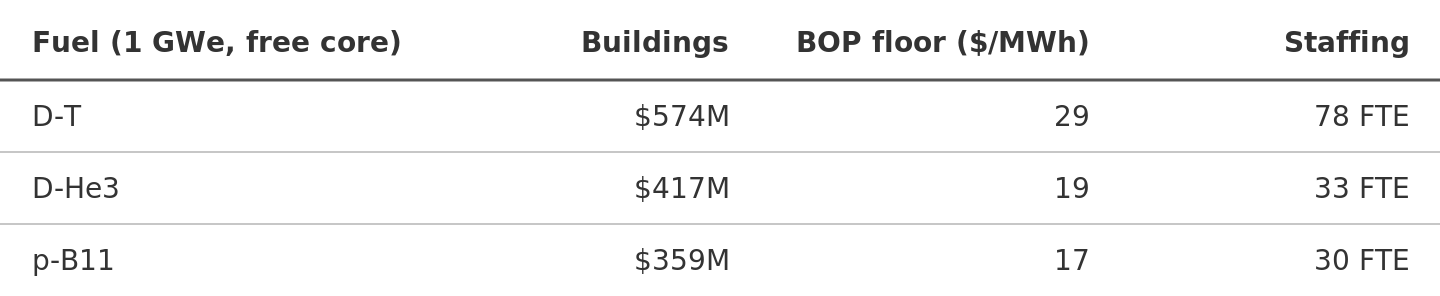
Deuterium-helium-3 (D-He3) produces about 6% of its energy as neutrons from D-D side reactions, far less than D-T, but not zero. The buildings require some radiation shielding and modest tritium monitoring, bringing them to $417M. The BOP floor drops to $19/MWh. However, D-He3 carries a separate problem: helium-3 fuel at an optimistic $2M/kg (used in this analysis) contributes $48/MWh to the levelized electricity cost. The DOE-allocated price is roughly $4.5M/kg (Congressional Research Service, 2010), which would more than double this. The BOP is competitive but the cost of fuel is challenging. Unlike tritium, which can be bred in a lithium blanket surrounding the same reactor that consumes it, helium-3 breeding would likely require a separate D-D fusion source: a working fusion reactor to fuel the primary fusion reactor.
Proton-boron (p-B11) fuel is aneutronic: 99.8% of its fusion energy comes out as charged alpha particles, not neutrons. It uses no tritium and does not activate structural components. The buildings can be built to conventional industrial standards: no shielding, no hot cells, no tritium containment infrastructure. The result is a BOP floor of $17/MWh, well below half the D-T floor. Staffing requirements are similarly favorable: a p-B11 plant needs roughly the same staff as a conventional thermal plant plus fusion-specific roles (magnet technicians, vacuum systems, plasma control), but none of the radiation-specific roles that dominate D-T. No health physics, no tritium processing, no radwaste, and no hot cell operators.
The $215M building cost gap between D-T and p-B11 is larger than most fusion core cost-reduction scenarios in the literature. This gap is not a reflection of the plasma physics difficulty. It is the implication of what handling neutrons and tritium does to the cost of the building you put the plant in. The fuel choice establishes the floor before the fusion core enters the picture.
With zero He-3 fuel cost (self-bred), a D-He3 plant without a core is slightly more expensive than p-B11 ($18.9/MWh vs $17.3/MWh) due to the modest shielding required for D-D side reaction neutrons.
Lowering the p-B11 Floor
The p-B11 baseline floor is $17/MWh, still 1.7x the target, but closer than D-T. Applying the same parameters:
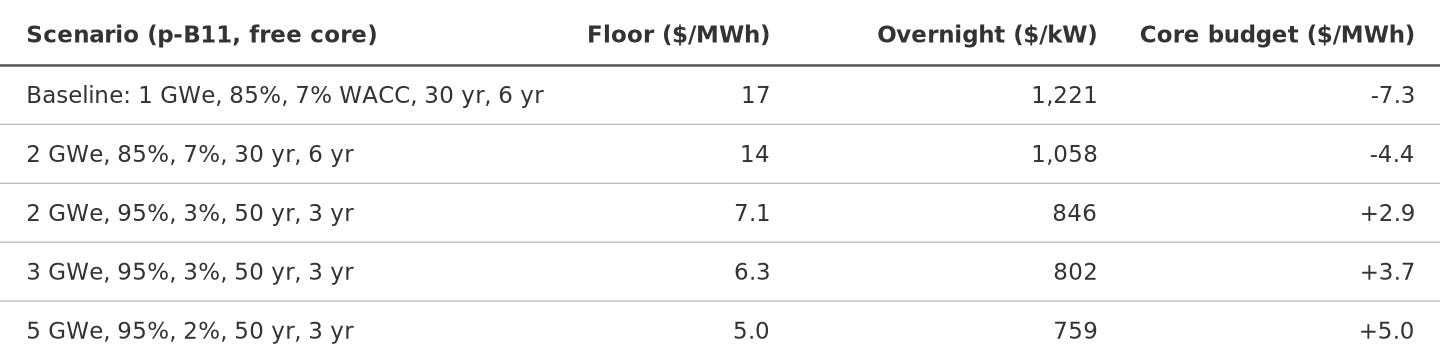
At 2 GWe with 95% availability, 3% WACC, 3-year construction, and 50-year life, the p-B11 floor drops to $7/MWh (below the target), leaving $2.9/MWh for the fusion core. Compare this to D-T at the same conditions: $14/MWh floor at full staffing, or $10/MWh with staffing halved, leaving no budget for the core either way.
Is 3-year construction realistic for the BOP? Modern gas combined-cycle plants of comparable scale are built in 2-3 years. The BOP of a fusion plant is similar in scope and complexity. In the scenario we are solving for, we do not construct the fusion core, only the turbine halls, cooling systems, switchgears, and buildings. A 3% WACC is not realistic for an unsubsidized first-of-a-kind plant; commercial project finance for new energy technologies typically runs 7-10%. But government-backed financing (DOE Loan Programs Office, export credit agencies) routinely achieves 2-4% for qualifying infrastructure. The Vogtle nuclear expansion, for example, received an $8.3B DOE loan guarantee. Reaching 3% WACC assumes the plant is financed as infrastructure.
At the 2 GWe aggressive conditions, the remaining budget for the fusion core is $2.9/MWh, roughly $1,112/kW of overnight capital for magnets, heating, vacuum vessel, structure, power supplies, and installation. For reference, the entire overnight cost of a natural gas combined-cycle plant is $900-1,200/kW. The fusion core has to fit within that budget while being none of those things (mature, mass-produced, or built at scale) yet.
O&M staffing accounts for $3.2/MWh of the $7.1/MWh p-B11 floor, about half. But unlike D-T, p-B11 is already below the 1-cent target at full staffing. No automation is required to reach $10/MWh. Because p-B11 has no radiation-specific roles, the staffing automation argument is much stronger here, and the gains go directly to widening the core budget. The remaining functions (grid dispatch, routine maintenance, unplanned fault response) are the same as any conventional thermal plant. Highly automated operation could bring staffing from 30 to 15 employees, dropping the floor from $7.1 to $5.5/MWh.
Radical staffing reduction also reduces the building costs. A 15-FTE plant still needs a control room, canteen, locker rooms, parking. A near-zero-FTE plant looks more like a data center: remote monitoring, automated systems, minimal human-occupied space. That could strip $50-100M from the $359M building cost, flowing directly into overnight capital and LCOE. Together, near-zero staffing and the associated building scope reduction would drop the floor from $7.1/MWh to roughly $4.3/MWh, leaving $5.7/MWh of budget for the fusion core. At the limit, automation does not just reduce O&M; it removes building scope.
Structurally Changing the Floor with Direct Conversion
The preceding analysis assumes a thermal cycle: fusion produces heat, a turbine converts heat to electricity. The turbine, cooling towers, and the buildings that house them are the floor. But for aneutronic fuels, this assumption is optional.
Aneutronic fuels such as D-He3 or p-B11 produce the majority of their fusion energy as energetic charged particles. These particles can, in principle, be converted directly to electricity without a thermal cycle. Direct energy conversion removes the need for the turbine, the cooling towers, and much of the building. It fundamentally changes the floor. This is not a theoretical curiosity. Helion Energy’s approach to D-He3 fusion is predicated on direct energy conversion: pulsed field-reversed configurations that capture fusion energy inductively, without a steam cycle.
If direct conversion works at the anticipated efficiencies, the BOP costs contributing to the floor described in this post are reduced or eliminated: the plant is the core, a power conditioning system, and a grid connection.
Direct energy conversion is less mature than thermal conversion, and its cost uncertainty is much larger. The efficiency, capital cost, and reliability of direct conversion at utility scale are open questions. We will explore the economics of direct conversion in a future post.
Conclusions
1. D-T floor can reach $10/MWh, but the margin is razor-thin. At 5 GWe with the most aggressive financial conditions, D-T crosses $10/MWh with current staffing, but leaves no budget for the core. At 2 GWe, it requires cutting staffing to about half of current levels. The buildings ($574M), radiation-specific staffing, and the procedures required to handle neutrons and tritium eat most of the budget. D-T can reach the target, but only at extreme scale with favorable financing, and with negligible budget for the fusion core.
2. Fuel choice is a buildings-and-staffing decision, not just a core decision. The BOP equipment subtotal is essentially fuel-invariant (roughly $386M for all three fuels); the fuel-driven leverage is in buildings and staffing. The $215M building cost gap between D-T ($574M) and p-B11 ($359M) is larger than most fusion core cost-reduction scenarios. Aneutronic fuel downgrades the buildings from enhanced-industrial to industrial, and removes tritium infrastructure entirely. These savings compound through indirect costs and financing. The D-T floor ($29/MWh) is roughly 70% higher than the p-B11 floor ($17/MWh). The D-He3 floor falls in between on BOP ($19/MWh) but is burdened by helium-3 fuel costs.
3. No single parameter reaches $10/MWh. At standard financial conditions, even the p-B11 LCOE floor is 1.8x the target with a free fusion core. Reaching $10/MWh requires at least four favorable conditions simultaneously: scale (2+ GWe), high availability (95%+), low-cost financing (3% WACC or below), and fast construction (3 years or less). Each of these is individually achievable. Together they represent a systems integration challenge as much as an engineering one.
4. Scale matters more than unit cost. Going from 1 GWe to 2 GWe buys more LCOE reduction than any other single parameter. Staffing scales as P^0.5, so a 2 GWe plant needs 1.4x the staff of a 1 GWe plant, not 2x. This economy of scale does not depend on any technology breakthrough.
5. Direct conversion could change the floor. For aneutronic fuels, direct energy conversion bypasses the thermal cycle, the largest single component of the floor. If it works at the projected efficiencies, the economics of fusion fundamentally change: from pushing down a floor to building an altogether different kind of power plant.
The Path Forward
The lower bound is a useful limit case. No fusion core will be free. But the exercise reveals where the constraints on ultra-low-cost fusion power lie: not in the fusion core, but in the industrial cost structure around it.
A p-B11 fusion plant at 2 GWe scale, with 95% availability, 3% cost of capital, 3-year construction, and 50-year life, has a balance-of-plant floor of $7.1/MWh and a fusion core budget of $1,112/kW. That budget is extremely tight, and it grows with scale.
Reaching $10/MWh fusion energy is a whole-plant problem. It requires large plants, high availability, fast construction, low-cost financing, long plant life, and a fuel that does not burden the balance of plant with radioactivity safety requirements. Every component of this path (industrial buildings, large turbines, high-availability operations, government-backed financing, long-lived civil structures) has existence proofs in other industries and at the required scale.
The fusion core is the hard part. The BOP floor tells us how inexpensive the power it ultimately generates could be.
References
Najmabadi, F. et al. “The ARIES-AT advanced tokamak, Advanced technology fusion power plant.” Fusion Engineering and Design, 80, 3-23 (2006). Link
Entler, S. et al. “Approximation of the economy of fusion energy.” Energy, 152, 489-497 (2018). Link
Sheffield, J. & Milora, S. “Generic Magnetic Fusion Reactor Revisited.” Fusion Science and Technology, 70(1), 14-35 (2016). Link
Lindley, B. A. et al. “Can fusion energy be cost-competitive and commercially viable? An analysis of magnetically confined reactors.” Energy Policy, 177 (2023). Link
Tang, L. et al. “Fusion power experience rates are overestimated.” Nature Energy (2026). Link
U.S. DOE/NETL. “Cost and Performance Baseline for Fossil Energy Plants, Volume 1.” DOE/NETL-2022/3575 (2022). Link
Waganer, L. “ARIES Cost Account Documentation.” UCSD-CER-13-01 (2013). Link
Woodruff, S. “A Costing Framework for Fusion Power Plants.” arXiv:2601.21724 (2026). Link. Documents the pyFECONS methodology that 1costingfe builds on and replaces.
Shea, D. A. & Morgan, D. “The Helium-3 Shortage: Supply, Demand, and Options for Congress.” Congressional Research Service, R41419 (2010). Link
1cFE. “1costingfe: Open-source fusion techno-economic model.” GitHub
Where does General Fusion’s Magnetized Target Fusion approach fall here?
I always liked their molten lead-lithium internal working fluid that supposedly should act as a neutron absorber and tritium breeder.
Would this lessen the radiation needs of the standard tokomak or not much for long-term operation?
Sell heat and you'll improve by a factor 4